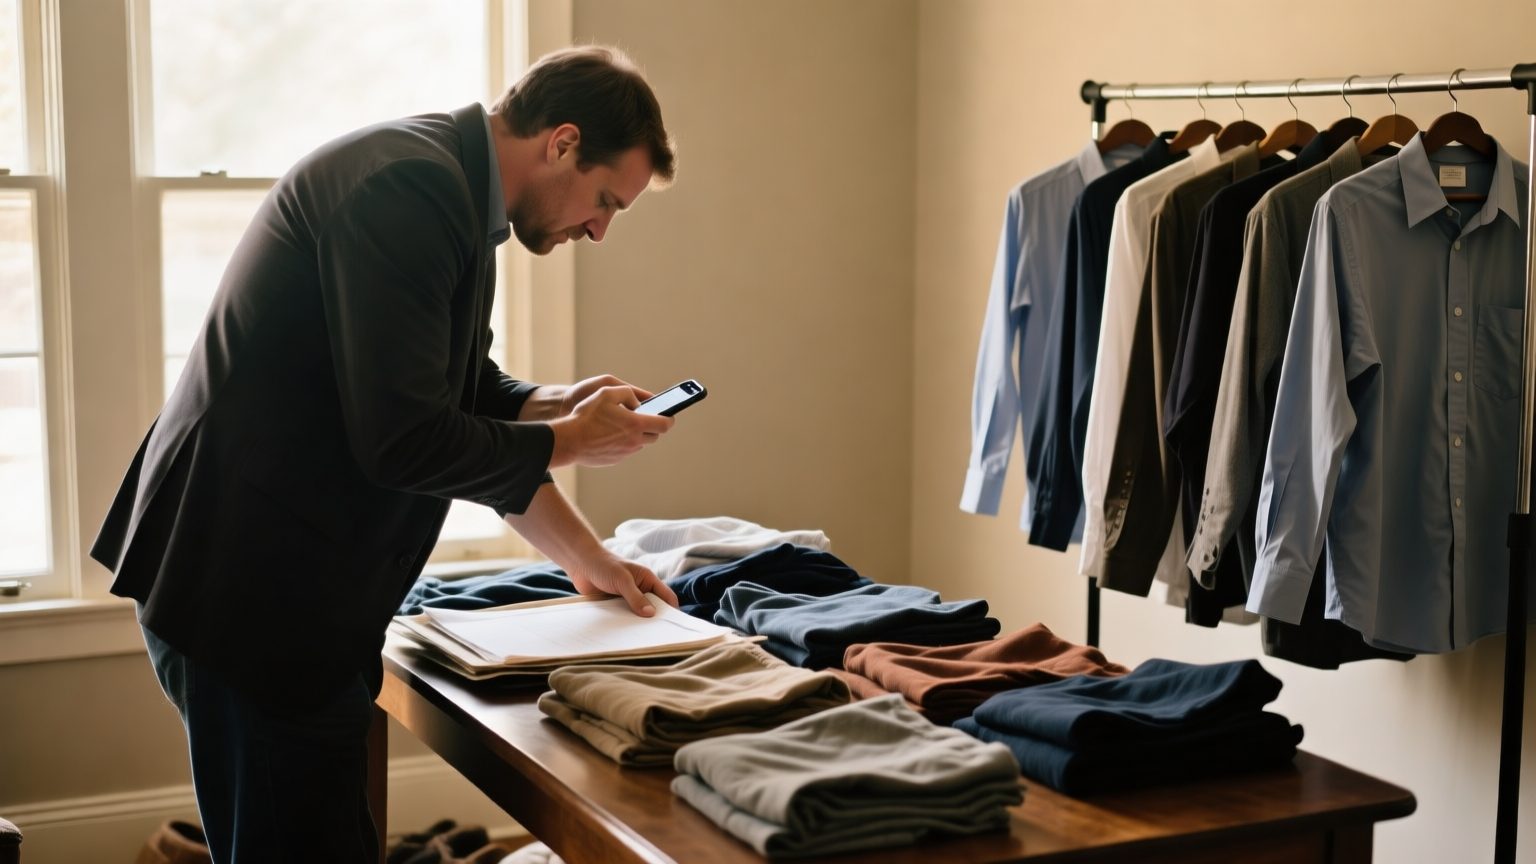
Why clothing is the hidden bottleneck on a large-loss contents claim
On a total-loss fire or a major water event, clothing is rarely the most valuable category, but it is almost always the highest in item count. A single closet holds dozens of shirts, pants, dresses, shoes, coats, and accessories, and a family home holds several closets. A 2,000-item contents inventory can be half clothing before you reach the furniture, electronics, or kitchen.
That volume is the problem. Each garment is easy to value on its own, but pricing hundreds of them one at a time, looking up a current retail equivalent for each, is where a contents file stalls. The goal is to value the wardrobe accurately without treating every sock as a research project, while still keeping each value defensible when a reviewer opens the file.
Group first, then price: the category and quality-tier method
The fastest defensible way to handle a large wardrobe is to group before you price. Sort the clothing into categories, then split each category into quality tiers, because a fast-fashion t-shirt and a tailored dress shirt are not the same replacement cost even though both are shirts.
| Category | Quality tiers to separate | Why it matters for RCV |
|---|---|---|
| Tops (shirts, blouses, sweaters) | Basic / mid / premium or designer | Replacement price ranges widely by tier |
| Bottoms (jeans, slacks, skirts) | Basic / mid / premium | Denim and tailored items price very differently |
| Outerwear (coats, jackets) | Everyday / technical / premium | High per-item value, worth itemizing more finely |
| Footwear | Casual / athletic / dress or designer | Brand drives replacement cost more than category |
| Accessories, undergarments, basics | Group as sets where reasonable | High count, low unit value; group to save time |
Within each category and tier, count the quantity, then price the group to a current retail equivalent of like kind and quality. This is the same standard that governs any contents replacement, explained in more depth in our guide to matching contents replacements so your RCV holds up. You are not required to find the exact garment that burned. You are required to find a comparable one, at a comparable quality, at today's price, and to record where the price came from.
Getting replacement cost value right on clothing
Replacement cost value is what it costs to buy a similar new garment at current prices, before depreciation. If you are new to the term, our explainer on what replacement cost value means covers it in plain terms. For clothing specifically, a few rules keep the values clean:
- Price to the tier, not the label you cannot verify. If a shirt was clearly a premium brand and the homeowner confirms it, price it there. If you cannot establish the brand, price it to the quality you can see.
- Use a real, current retail source for each group and record it. A value with a source behind it is easy to review. A value with nothing behind it invites a cut.
- Keep quantities honest. Overstating counts on high-volume basics is a common reason a reviewer sends a clothing schedule back.
Depreciation and condition on a wardrobe
Clothing depreciates for age, wear, and condition, and the actual cash value is the replacement cost minus that depreciation. There is no single official schedule that dictates a clothing depreciation percentage, so adjusters commonly apply depreciation by group of similar items and by the age and condition recorded for each. Reference tools such as the Claims Pages depreciation guides and carrier explainers like Understanding Depreciation show how age and condition drive the reduction. Whether that depreciation is recoverable, and when, is governed by the policy: many policies pay actual cash value first and release recoverable depreciation after the items are replaced and proof is submitted. Your policy language is what governs how and when replacement cost is paid.
The practical takeaway for a large wardrobe: capture age and condition at the group level so depreciation is applied fairly and consistently, rather than guessing item by item at the end. Documenting age and condition well is its own discipline, and the same care you would apply to a single valuable item is what keeps a full wardrobe defensible, which our guide on valuing used household items walks through.
What to document so a clothing schedule holds up in review
A clothing schedule survives review when each line, or each grouped line, carries the same four things any contents value needs: a clear description including category and quality tier, the quantity, a current replacement price with its source, and the age and condition used for depreciation. When a total-loss fire leaves nothing to photograph, that documentation is reconstructed from what the homeowner can recall and confirm, which is covered in our guide to documenting contents after a fire. The evidence behind each group is what turns a large, fast-moving clothing schedule into a file a reviewer can accept without a round of questions.
How Contensure helps with high-volume clothing
Contensure is built for exactly this volume problem. It takes photos, item lists, spreadsheets, and claim files, drafts item descriptions and groups them by category and quality, researches replacement cost values from real retailer data, and attaches the source evidence to each value. Your team reviews and signs off before anything is final, because AI drafts and professionals review. It handles the repetitive per-item research that makes a large wardrobe slow, so a contents professional spends time on judgment rather than browser tabs. It complements your existing packout and estimating workflows rather than replacing them, and how it fits with those tools is documented across the Contensure blog. Claim data is handled carefully, and you can review how Contensure handles security before you upload a file. If you want to see it on your own large-loss claim, you can talk to Contensure.